What Is a Tenant Credit Check? A Guide for Landlords and Letting Agents
Almost every tenancy in the UK starts with a credit check. Most landlords know it’s something they should do. Fewer could say exactly what one contains, what it proves, or what it quietly misses.
This guide covers what a tenant credit check actually looks at, the anti-money laundering and fraud checks that usually sit alongside it, and why both matter when you’re deciding who to hand your keys to.
What is a tenant credit check?
A tenant credit check is a search of a prospective tenant’s credit record, carried out by a referencing provider on behalf of a landlord or letting agent. It draws on data held by one of the UK’s credit reference agencies: Equifax, Experian or TransUnion.
The check does two things at once. It confirms the applicant is a real person living at the addresses they’ve given you. It also shows how they’ve handled credit commitments in the past, including any court judgments or insolvency on record.
It isn’t a pass or fail test, though it’s often described that way. The report gives you evidence, and the decision stays with you.
What does a tenant credit check show?
Identity and address history
The check matches the applicant’s name, date of birth and addresses against the electoral register and their credit record. If they’re not on the electoral roll, credit agreements and past credit applications can confirm the link instead.
A linked address search can also uncover addresses the applicant didn’t mention. This matters more than it sounds. An address left off an application is sometimes just forgetfulness, but it can also be where an unpaid debt or an unhappy former landlord sits.
Credit history and score
You’ll see a credit score, which is a summary of the applicant’s overall credit risk, together with the detail behind it. That usually covers credit accounts, payment history and how recently they’ve applied for credit.
A pattern here matters more than any single entry. Someone who has missed one payment during a house move is in a different position from someone who has consistently fallen behind over two years.
Public record information
The report also shows court and insolvency records:
- County Court Judgments (CCJs). Issued when someone has been taken to court over an unpaid debt. In England and Wales these stay on file for six years. The Scottish equivalent is a decree.
- Bankruptcy, Individual Voluntary Arrangements (IVAs) and Debt Relief Orders (DROs). All formal insolvency arrangements, and each remains on file for six years from the date it started.
Age and status matter. A satisfied CCJ from four years ago tells you something very different from an unpaid one issued last month.
What a credit check doesn’t tell you
This is where landlords are most often caught out. A credit check won’t tell you:
- Whether the applicant can afford this rent. Credit files don’t show income. An applicant can have a spotless record and still be stretched by your rent.
- How they treated their last home. Rent payments generally don’t appear on credit files unless the tenant has opted into a rent reporting scheme. Past landlord behaviour comes from a landlord reference, not a credit search.
- Whether they have the right to rent. Right to Rent is a separate legal check on immigration status, required of landlords in England.
- Anything about their character or criminal record. Referencing providers have no access to criminal records for tenancy purposes.
This is why a credit check is usually the start of referencing rather than the whole of it. A Full Tenant Profile adds verified income, employment confirmation and a previous landlord reference on top.
The AML and fraud checks that come with it
Most professional tenant credit checks, including ours, run a set of anti-money laundering (AML) and fraud searches at the same time. These aren’t about creditworthiness at all. They’re about who the person is and whether it’s lawful and safe to do business with them.
Sanctions screening
The UK Sanctions List names individuals, entities and ships subject to UK sanctions, and is published by the Foreign, Commonwealth and Development Office. Since January 2026 it’s the single source for all UK sanctions designations, replacing the OFSI Consolidated List that many firms previously screened against.
If someone is subject to an asset freeze, it’s a criminal offence to make funds or economic resources available to them. That includes letting them a property. These rules apply to everyone in the UK, not just regulated businesses, so a private landlord is as exposed as a large agency. A match is rare, but the consequences of missing one are severe, which is why it’s screened as standard.
Politically Exposed Persons (PEPs)
A PEP is someone who holds a prominent public position, or who is a close relative or associate of someone who does. Being a PEP is not a black mark and isn’t grounds for refusing a tenancy. It simply flags that the person’s finances warrant a closer look, since public roles can carry a higher bribery and corruption risk. In practice it usually means asking a few more questions about the source of funds.
Fraud database checks
CIFAS is the UK’s main fraud prevention database, and a marker against an identity means fraudulent activity has been recorded. Read these carefully. Some markers are Protective Registrations, which people add themselves after their identity has been stolen. That’s a sign of caution on their part, not dishonesty.
Deceased register checks
A search against a deceased persons register flags where an applicant’s details match someone who has died. Using a dead person’s identity is a well-established fraud technique, and this check is one of the more reliable ways to catch a fabricated applicant.
Do letting agents have to do AML checks?
Some do, by law. Letting agency businesses fall under the Money Laundering Regulations where a tenancy runs for a month or more and the rent reaches the threshold set in the regulations, currently equivalent to around £10,000 a month per property. Agents who meet that test must register with HMRC and carry out customer due diligence on both the tenant and the landlord. Estate agency businesses are covered regardless of value.
Most residential tenancies sit well below that threshold. But sanctions law applies to every letting, and industry bodies including Propertymark encourage agents to apply consistent due diligence across all customers rather than only the high-value ones. Screening as part of routine referencing is the simplest way to achieve that.
Why landlords and letting agents run credit checks
Arrears are expensive. Recovering possession from a non-paying tenant takes months, and you’re unlikely to see the lost rent again. A check costing a few pounds is cheap by comparison.
Identity fraud is real. Rental fraud ranges from someone inflating their income to organised use of stolen identities to obtain a property for criminal use. Verified identity is the foundation everything else rests on.
Insurers expect it. Rent protection policies require tenants to have been referenced to a set standard. Skip the check and you may find a later claim rejected.
It keeps your decisions consistent and fair. Applying the same check to every applicant, and recording why you decided as you did, is your best defence if a decision is ever questioned. Under the Equality Act 2010 you can’t refuse someone because of a protected characteristic. In England, the Renters’ Rights Act also prohibits refusing tenants simply because they receive benefits or have children. Decisions need to rest on evidence such as affordability.
There’s less room to fall back on. With limits now in place in England on how much rent can be taken in advance, the old habit of asking for six months up front from a weaker applicant is no longer available. Getting the assessment right at the referencing stage matters more than it used to.
Where the credit check fits in the referencing process
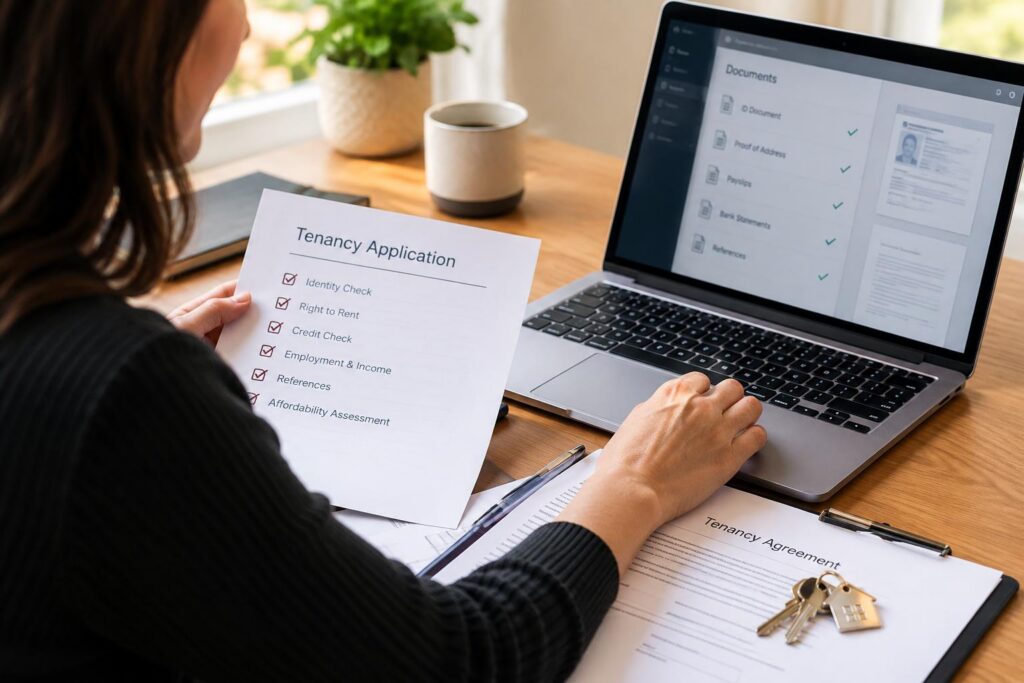
For most landlords and agents the sequence looks like this:
- Application. Collect the applicant’s details, including address history.
- Credit and identity check. A fast first filter, usually returned the same day, covering credit history, ID and the AML searches above.
- Affordability assessment. Compare verified income against the rent. Our free Rent Affordability Calculator gives you a quick view.
- References. Employment and previous landlord references fill in what the credit file can’t tell you.
- Right to Rent. A separate legal requirement for landlords in England, completed before the tenancy begins.
- Decision. Accept, decline, or accept with a guarantor.
A weak credit result doesn’t have to end the application. A guarantor, who is themselves checked and assessed for affordability, is the usual way to make a borderline let work.
What tenants should know
If you’re applying for a tenancy, a credit check as part of referencing is normally recorded as a soft search. You’ll see it on your own credit report, but lenders won’t, and it won’t affect your credit score.
You also can’t be charged for it. Charging tenants for referencing or credit checks is banned under the Tenant Fees Act 2019 in England, with equivalent rules in Wales and Scotland. The landlord or letting agent pays.
It’s worth checking your own credit report before you apply, since you can get it free from all three credit reference agencies. Errors do occur, and correcting one before an application is far easier than arguing about it afterwards.
Getting started
A tenant credit check is a small cost that prevents some very large ones. It confirms who your applicant is, shows how they’ve handled money, and clears the legal checks that every letting depends on.
You can run a tenant credit check here, with reports returned within 2 hours. If you’d like to talk it through first, call our team on 01793 847014.